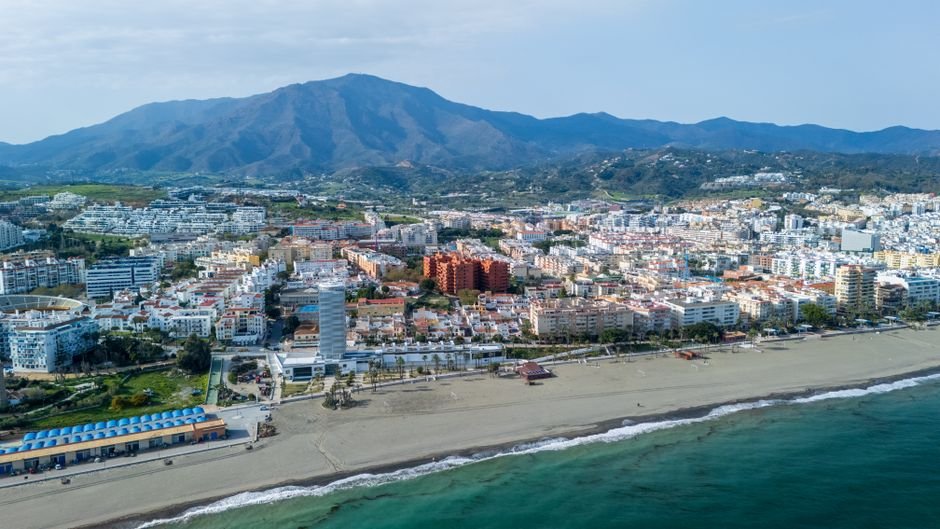
The average property prices in Estepona exceed €4,200 per square meter, compared to the national average of €2,071 per square meter published by Tinsa. This situation means that even a modest mortgage of €300,000 necessitates nearly €90,000 in savings and requires couples to allocate up to 35% of their combined income towards monthly payments.
In Estepona, the housing crisis is evident even without discussing million-euro villas. A two-bedroom apartment priced at €300,000, typically viewed as affordable in other municipalities, reflects a daunting challenge for many couples. Recent figures from Idealista and Fotocasa indicate that home prices in Estepona have surged above €4,200–€4,500 per square meter as of August 2026, with the median cost for apartments in the 29680 postal code nearing €392,000.
In stark contrast, Tinsa reports the average price for new and existing homes across Spain at around €2,071 per square meter. This discrepancy suggests that a standard apartment in Estepona costs nearly double the national average, all while local salaries have not experienced a proportional rise. Consequently, to consider purchasing a property priced at €300,000, a couple would need a net monthly income of approximately €4,000, significant savings, and a mortgage burden bordering on the limits suggested by financial regulators.
Financial guidelines recommend that mortgage payments should ideally not exceed 30% to 35% of a household’s net income, with total debt obligations remaining under 40% to avoid financial risk. For a €300,000 home in Spain, Fotocasa estimates that with fixed interest rates around 3.5% and terms spanning 25–30 years, monthly payments would fall between €1,350 and €1,500, necessitating a minimum household income of about €4,500–€5,000 for a 30% effort rate.
Other simulations, such as those from Hipotecas100, indicate that a 30-year fixed-rate mortgage of €300,000 at approximately 2.1% results in monthly payments close to €1,124, which also requires an income between €3,200 and €3,500 to maintain a 30-35% effort rate. Practically, this means that the entry threshold for a €300,000 property in Estepona is a minimum combined net income of €3,500–€4,000, assuming no other significant debts. With the rising cost of living in the Costa del Sol and uncertainty surrounding interest rates, the actual financial margin becomes even tighter.
Additionally, potential buyers must consider the upfront savings needed: banks and experts recommend having at least 20% of the property’s value as a down payment, along with another 10-15% for associated costs such as taxes, notary fees, and registration. In the case of a €300,000 home, this translates to needing roughly €90,000 before signing the mortgage. Thus, the average home in Estepona requires not only a €4,000 combined income but also savings equivalent to nearly three years of that income, a reality that excludes many young couples, service sector workers, and residents who have not benefitted from rising wages and wealth.
In response to soaring prices that render average housing a luxury, Estepona’s City Council has adopted an ambitious narrative around protected housing. Plans include 36 municipal parcels designated for affordable housing, with theoretical capacity for 738 units, and the tendering of two plots on Camino de Cortes Norte for 199 protected homes, in addition to 117 more in the same area. On paper, this amounts to over 300 protected units in Camino de Cortes alone, with further projects planned in Camino de Monterroso and Guadalobón.
However, the fine print reveals a potentially limited impact compared to the political rhetoric. Many of these projects remain in licensing, bidding, or planning stages, with timelines that do not align with the urgent needs of current home seekers. Moreover, while the City Council sets maximum prices for tendered parcels, the actual awarding of contracts depends on private developers submitting competitive and profitable offers, which introduces market dynamics into a scheme branded as ‘social.’
As a result, the reality of protected housing risks becoming an institutional showcase: numerous figures, announcements, and potential future developments presented in reports, yet very few actual keys handed over to families who witness €300,000–€400,000 promotions slipping out of reach in real-time. Despite a flurry of press releases heralding a ‘historic push’ for protected housing, access to reasonably priced homes continues to hinge on economic conditions—salaries, job stability, and savings—that align with the exclusionary dynamics of the free market.
From the perspective of new construction catalogs, Estepona appears to be thriving: developments feature pools, gyms, sea views, sprawling terraces, and ‘luxury quality’ at prices that still seem ‘competitive’ compared to cities like London or Paris for international investors. However, analyzing local statistics—average incomes, contract types, the weight of the service sector, and the temporary nature of tourism jobs—paints a different picture of the city, particularly for residents who work year-round and do not fit the profile of couples earning €4,000–€5,000 monthly with €90,000 in savings.
The requirements for protected housing further emphasize this divide: to qualify for affordable homes, applicants must meet a series of conditions regarding maximum income, residency, family composition, and not owning another property, thereby excluding those who have achieved a measure of stability but do not meet the income criteria for free market housing. This creates two distinct paths: one very narrow for those who meet the protected housing criteria, and another very costly for those navigating the free market, with virtually no intermediate options.
This gap leads to quiet decisions: couples forgoing children due to the inability to escape rental situations, young people moving to more affordable municipalities, workers commuting daily from less expensive towns, and families choosing to continue living with parents or in-laws longer than they would prefer. None of these realities are captured in the official narrative of a ‘grand push’ for housing in the city; yet they represent the everyday counterpoint to the statistics celebrated in press conferences.
Estepona’s plan for protected housing aims for 500 up to 2,000 units over four years. The rollout of these municipal affordable housing projects is undoubtedly a significant move, but the fundamental question remains: what urban model underpins this entire strategy? When planning regulations allow the allocation of land designated for public facilities to affordable housing, it partially corrects a previous design that prioritized high-end tourism and residential projects over accessible housing.
The paradox is that, even after releasing 36 parcels for 738 affordable homes, the predominant images representing Estepona externally remain of redeveloped promenades, four-star hotels, luxury-style developments, and rankings positioning the city as a favored destination for international buyers. Meanwhile, the stark reality is persistent: average housing prices hover around €4,000–€4,500 per square meter, the salary effort to purchase exceeds recommended limits in many Spanish provinces, and the opportunity cost of lacking a robust affordable rental policy accumulates year upon year.
The crucial debate is not merely about how many protected homes to build—300, 700, or 1,200—but rather how much land, urban gains, and political energy are being allocated to ensure that a person who works and lives in Estepona can afford decent housing without having to become an extraordinary economic success story. This is where the city must decide whether it wants to be, in the future, a resort with transient populations or a place where the daily lives of its residents have room, stability, and their own roof.
Interestingly, much of the institutional discourse on housing focuses on ‘new protected construction,’ state and regional plans, and images of future buildings, while few discuss the uncomfortable levers that could genuinely improve housing access in a city like Estepona. As the government approves a State Housing Plan for 2026–2030 with €7 billion allocated to expand public housing, rehabilitate existing properties, and provide rental assistance, the municipality remains heavily reliant on the free market, the logic of tourist rentals, and private investment to set reference prices.
In this context, there is a lack of very concrete discussions: how much land is effectively reserved for social and affordable rental, what portion of urban gains is reinvested in housing rather than just iconic facilities, what limits are set on tourist rentals in certain areas, and what roles could be played by models like housing cooperatives, shared ownership, or rent-to-own options on municipal land. Transparency is also lacking: knowing how many actual protected homes have been delivered, how many are in process, where they are located, and what percentage they represent of the total housing stock compared to the daily marketed properties priced between €300,000–€600,000.
Without this uncomfortable conversation, the city risks looking only upwards: more prices, more resorts, more investment, more photos of new projects, while a growing segment of its population looks down at budgets and expenses, realizing that owning a home has become a goal achievable only if one’s financial story fits the profile of a ‘successful couple’ with good salaries, few surprises, and savings that often do not match the reality of those who sustain Estepona’s daily life.